Independent business valuations. Every report signed and reviewed.
We value private businesses and company shares for Melbourne and Victorian owners, accountants and lawyers: buying and selling, partner exits and disputes, tax and CGT, and restructures. Valuation is the only service we provide.
- Melbourne office
- Level 7, 55 Collins Street
- Operated by
- Valuation Group Pty Ltd
- Fees
- Fixed in writing before work starts
Reviewed before it is signed.
Every report is reviewed by a second, suitably qualified business valuer before it is signed. Nothing leaves our office without that review. The aim is a value that is commercially realistic, supported by an accepted method, and traceable to the documents behind it.
Reports are signed by a named valuer, such as Jackson Wilson: B.Bus (Finance) · Diploma of Financial Services · RG146 · Disruptive Strategy (Harvard Business School Online)
See the work before you commit.
Each report is built so its numbers can be traced back to a document or a stated assumption, and the workings are set out, not held back. These pages are from our sample report: a complete report for a fictional company, marked SAMPLE on every page.
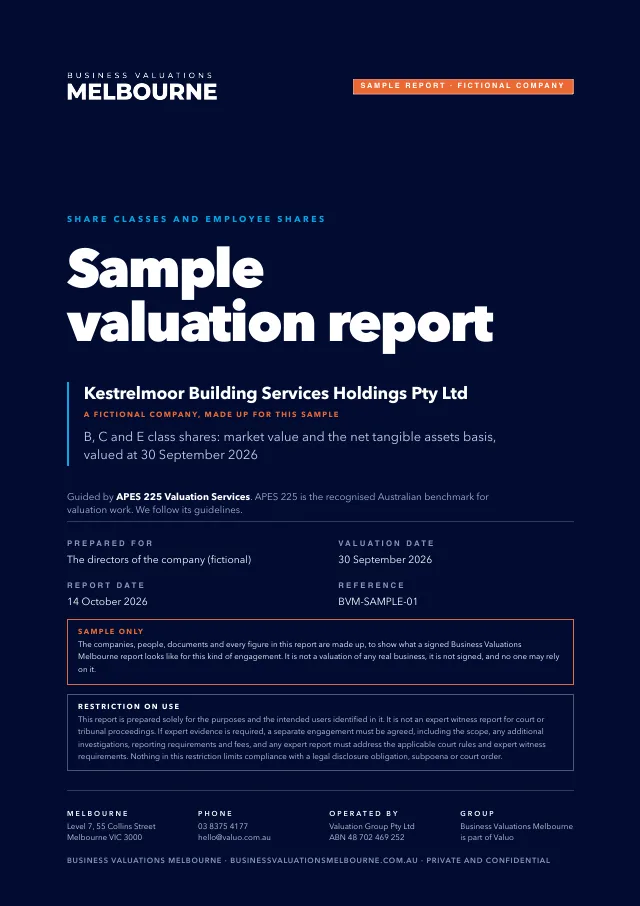 The coverWhat is valued, on what basis, and at what date.
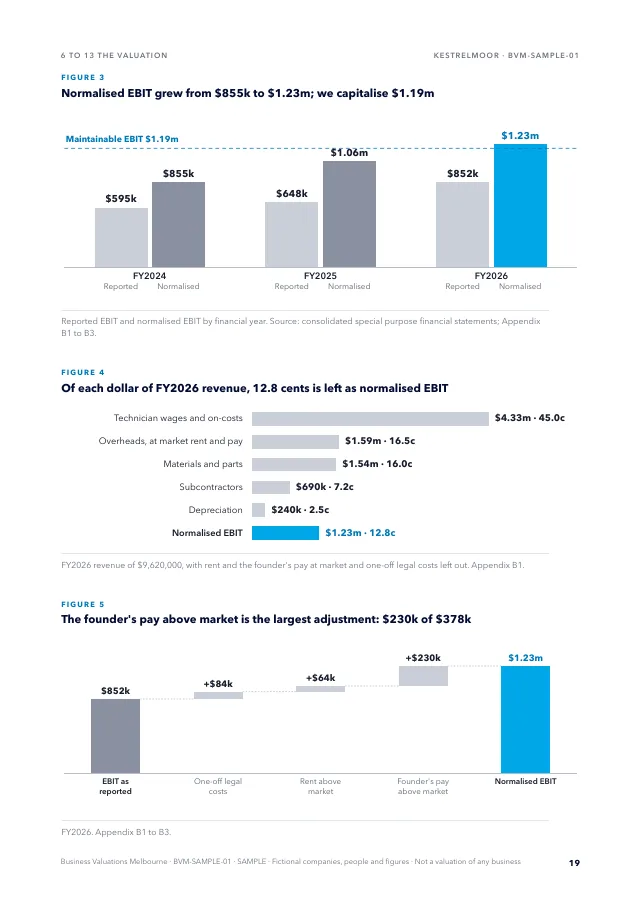 Page 19Earnings after adjustments, year by year.
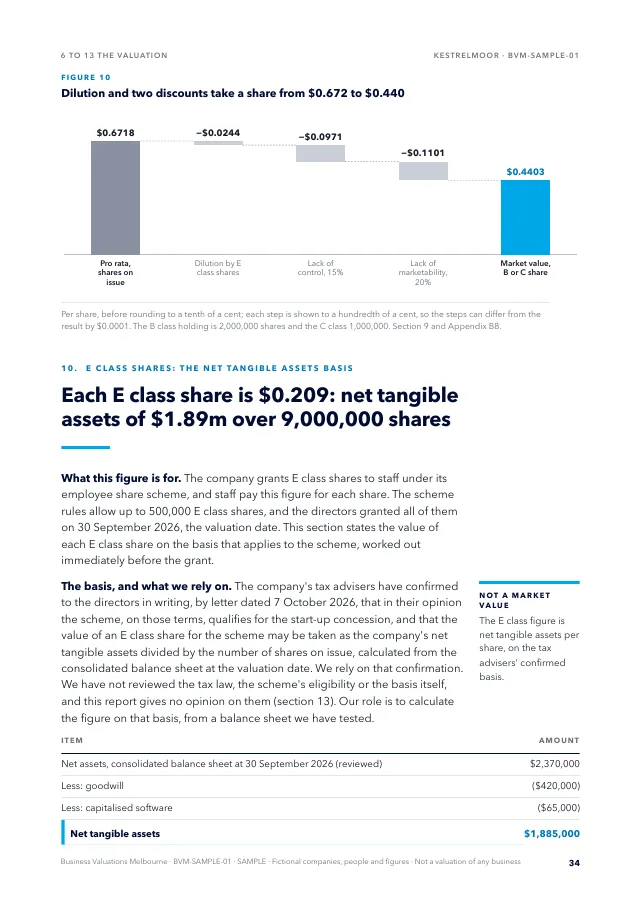 Page 34The value of each share, step by step.
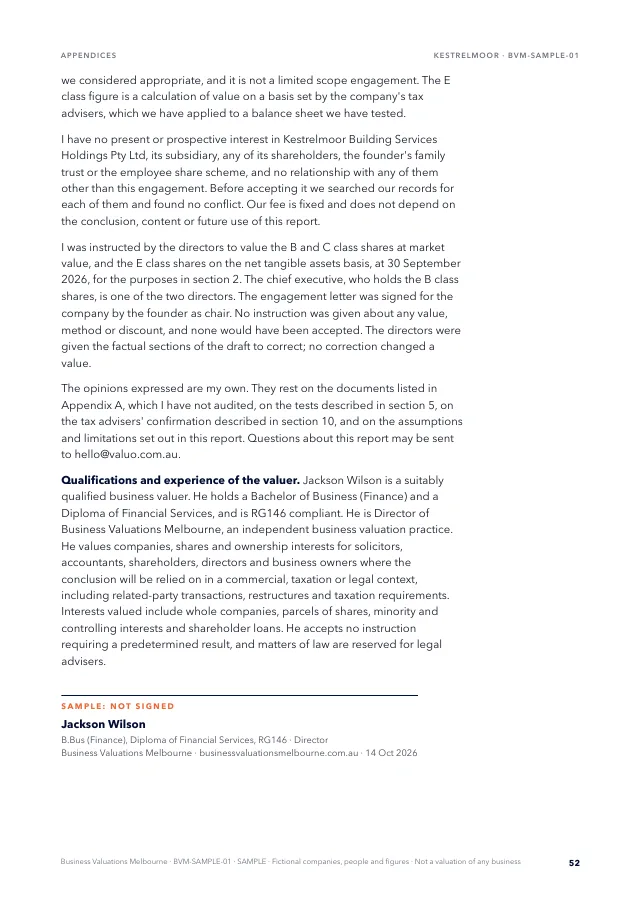 Page 52The valuer’s declaration: independence, conflicts and fee.
How the conclusion stays independent.
- 01The fee is fixed in writing for the agreed scope before work starts, and it is never tied to the result.
- 02We do not accept instructions that require a predetermined valuation result.
- 03We are never also your tax agent, auditor or broker.
- 04The report explains the methods considered and why one was adopted, and concludes on the value the evidence best supports.
- 05Where information cannot be independently verified, the report says so.
- 06Questions of law are left to legal advisers or the Court.
- 07Working papers are kept for ten years, so the file can answer questions if the valuation is ever reviewed.
Reports follow the guidelines of APES 225 Valuation Services, the standard Australia’s accounting bodies set for valuation work, and are prepared with the ATO’s market valuation guidance in mind.
The firm behind the report.
Business Valuations Melbourne is part of Valuo, a specialist valuation group, and is operated by Valuation Group Pty Ltd. Our valuers have prepared business valuations since 2014.
- Operating company
- Valuation Group Pty LtdABN 48 702 469 252 · ACN 702 469 252
- Melbourne office
- Level 7, 55 Collins Street, Melbourne VIC 3000Meetings by appointment. Most valuations run on documents and a call, anywhere in Greater Melbourne or regional Victoria.
- Phone
- 03 8375 4177Monday to Friday, 9am to 5:30pm Melbourne time
- [email protected]
- Family law
- Valuations for separation and family law proceedings are prepared through our dedicated family law practice, Family Law Valuations.
How a valuation is done.
For accountants, solicitors and anyone who wants the working detail.
The methods
The method follows the evidence and the economics of the business, and the report explains why the one adopted was chosen.
Sustainable earnings, after normalising owner pay, related-party arrangements and one-off items, capitalised at a multiple that reflects the risks of the business and the available market evidence.
Where future cash flows can reasonably be forecast and their timing and risk are material: growth and early-stage businesses, technology and IP-led companies, and businesses going through significant change.
Where tangible assets carry the value, earnings are negative or unreliable, or the company has stopped or materially reduced trading.
Comparable business transactions and industry multiples, considered in light of differences in scale, profitability, growth, concentration, owner dependence and risk.
What a valuation looks at
Not only the reported accounts, but the economics of the business as a buyer in the market would see them:
- ·Earnings: maintainable EBITDA and EBIT, after normalising proprietor pay, related-party expenses and abnormal or non-recurring items.
- ·Balance sheet: surplus assets and cash, net debt, working capital, shareholder and director loans, contingent liabilities and capital expenditure needs.
- ·Dependence: customer and supplier concentration, key-person and owner dependence, and recurring or contractual revenue.
- ·Risk and tenure: regulatory risk, lease obligations, franchise tenure and business-specific risk.
- ·The interest valued: control or minority, personal or transferable goodwill, and enterprise value versus equity value.
Each valuation works from the records: financial statements and management accounts, tax returns, general ledgers, payroll, loan accounts, share registers, constitutions and shareholder agreements, ASIC records, leases, contracts, franchise agreements, customer and supplier data, and forecasts.
Shareholder and dispute valuations
Where appropriate, a specific shareholding is valued on its own terms rather than as a mechanical percentage of the whole company: voting, economic and dividend rights, control, restrictions on transfer, the shareholder agreement and constitution, liquidity, any shareholder loans, and the circumstances around the interest.
Where shareholders, business partners or related parties disagree, the report keeps six things separate:
- 1Matters established from documentary evidence
- 2Information provided by management or the instructing party
- 3Assumptions
- 4Valuation judgment
- 5Matters capable of sensitivity analysis
- 6Matters of law requiring determination by legal advisers or the Court
Where a valuation is prepared for use in proceedings, the reader can identify the interest valued, the valuation date, the basis of value, the evidence relied on, the adjustments to the reported results, the method, the assumptions, the material sensitivities and the reasoning behind the opinion.
A standard report is not an expert witness report. If expert evidence is needed, a separate engagement must be agreed, including the scope and fees, and any expert report must address the applicable court rules.
Industries and typical work
- ·Medical centres, healthcare and allied health
- ·NDIS and disability services
- ·Professional services and consulting
- ·Real estate agencies and rent rolls
- ·Franchised businesses
- ·Technology and intellectual property
- ·Engineering, rail and mining services
- ·Retail and consumer products
- ·Trade and contracting
- ·100% of the shares in a private company
- ·A specific minority shareholding
- ·A company, for a shareholder separation
- ·A related-party transfer or ownership restructure
- ·Early-stage and intellectual-property-led companies
- ·Businesses with negative net assets or material debt
- ·Shareholder and director loans
- ·Owner dependence and customer concentration
- ·Personal and transferable goodwill
- ·Alternative assumptions and sensitivity analysis
What a report covers
A typical company valuation report covers:
- 1Instructions and purpose
- 2Valuation date
- 3Interest being valued
- 4Basis or standard of value
- 5Corporate and ownership structure
- 6Business background
- 7Historical financial performance
- 8Balance-sheet position
- 9Earnings normalisation
- 10Maintainable earnings
- 11Valuation methodology
- 12Market evidence
- 13Business-specific risk
- 14Enterprise value
- 15Net debt and surplus assets
- 16Equity value
- 17Value of the relevant shareholding
- 18Sensitivities and alternative assumptions
- 19Limitations and qualifications
- 20Valuation conclusion
What happens when you get in touch.
- 1Call or send the formCall 03 8375 4177 or send the form below. We reply within one business day.
- 2A fifteen-minute callWe confirm the purpose, the valuation date, the entities involved and the deadline.
- 3A fixed fee, in writingQuoted for the agreed scope before you commit. It is never contingent on the value concluded, on a transaction proceeding or on any tax outcome.
- 4The engagement letterWork starts once you accept it. It sets out the scope and the fee, and its terms govern the report and how it may be used.
Talk to a valuer
Tell us what you need valued.
A fifteen-minute call confirms the package, the fixed fee and the delivery date, before you commit to anything.
03 8375 4177Mon to Fri, 9am to 5:30pm Melbourne time
Send the form and we reply within one business day. No documents needed to start.
Small Business Valuation
$1,495 + GST
For a business with annual turnover under $2 million. Signed report in 2 business days. Delivery time starts once payment and all required information have been received. The fee is fixed in writing before we start and never tied to the outcome.
Larger business? Tell us in the form and we recommend the right package. All fees