Valuations for Melbourne manufacturers, from the factory floor to the order book.
For sales, succession, shareholder exits and restructures at manufacturers in Dandenong South, Braeside, Campbellfield, Laverton North and beyond.
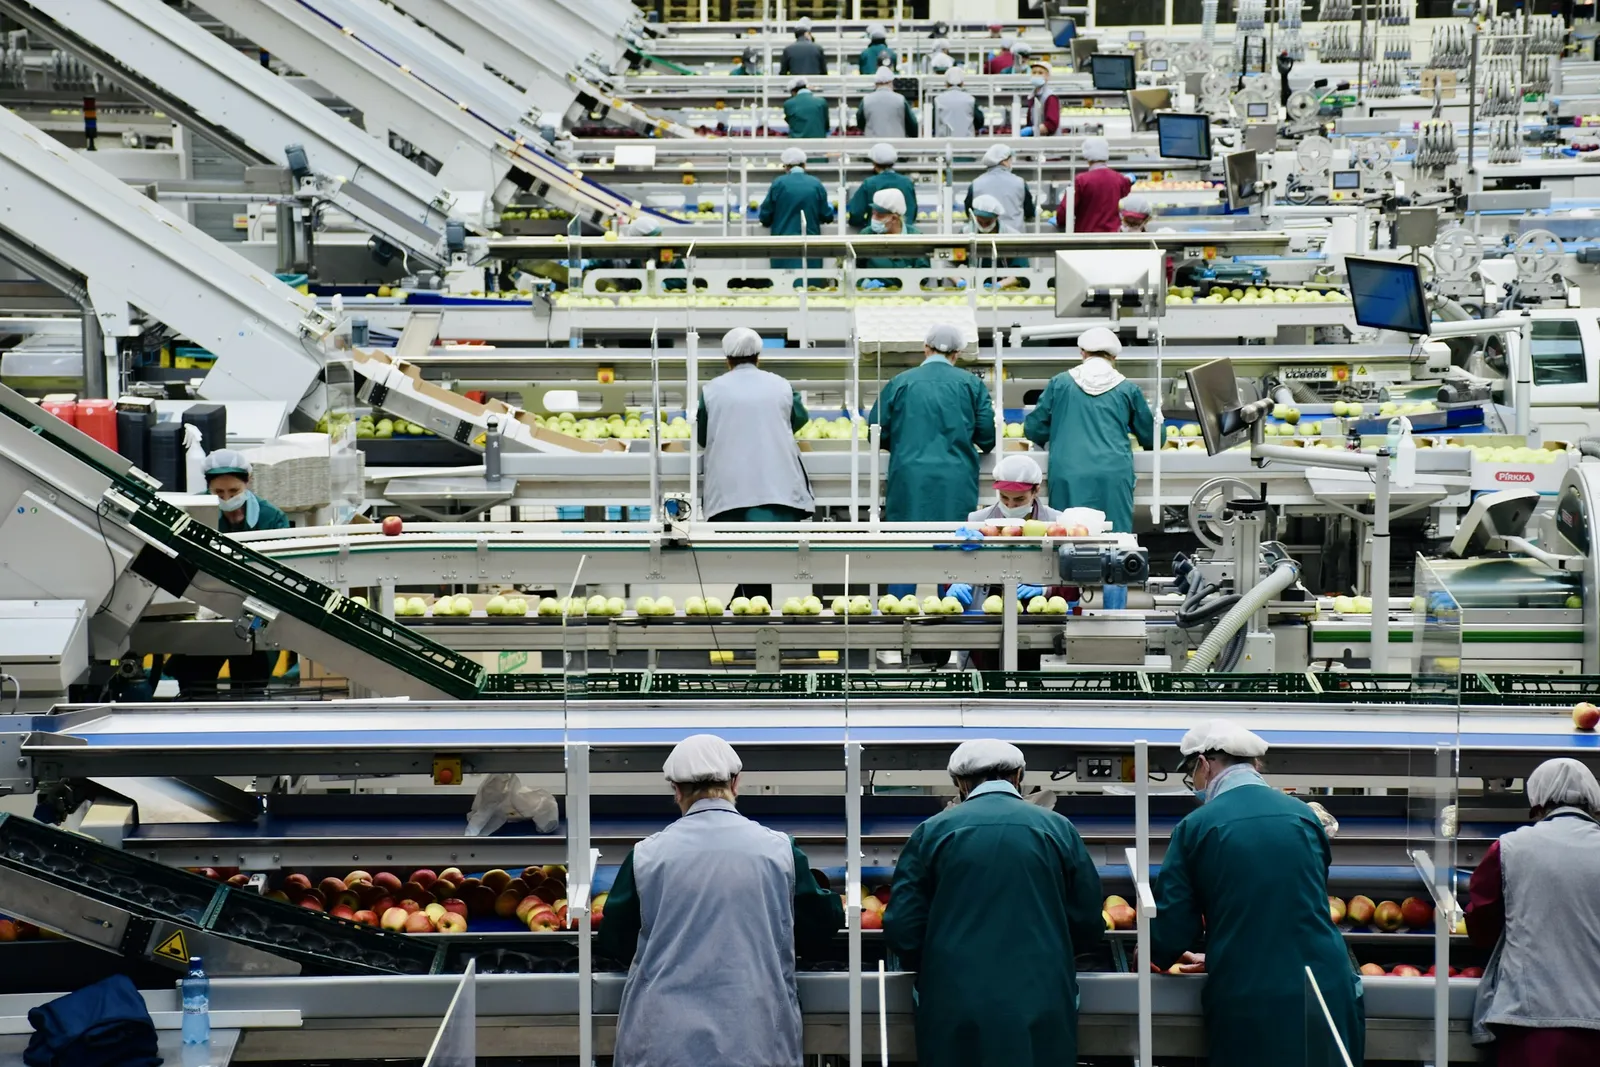
A Melbourne manufacturer is valued by testing what its earnings support against what its assets are worth, and concluding where the evidence is strongest. Plant, stock and sometimes the factory itself are real value, so our valuers check them at market rather than book value, separate owned premises from the trading business, and read the order book and customer list for how secure the earnings really are.
Earnings or net assets
A manufacturer holds machines on the floor, stock in the racks and often the building. That raises a question many valuations skip: is the business worth more as a going concern or as its assets? The valuation runs both. Earnings are measured after a realistic cost of replacing plant, because depreciation in a factory is a real cost, not an accounting entry. Plant is checked against recent appraisals or documented estimates, since written-down values after instant asset write-offs are often far from market. Where earnings do not support more than the assets, the report says so.
Owned premises in Dandenong South, Braeside or Campbellfield
Many Melbourne manufacturers own their factory through the trading company or a related entity. The valuation charges a market rent against earnings, values the business on that basis, and treats the property as a separate asset. Property is valued by a property valuer in Victoria; we value the business. Where the land sits inside a company or unit trust, Victorian property taxes come into the conversation too, and the next section sets out why.
Victorian property taxes a buyer's lawyer will raise
The SRO says landholder duty may apply when a person acquires an interest in a company or unit trust that holds Victorian land valued at $1 million or more, so a share sale of a manufacturer that owns its factory can raise a duty question even though no land title changes hands. Separately, under the commercial and industrial property tax reform, a commercial or industrial property that has a relevant entry transaction on or after 1 July 2024 moves to an annual tax, generally 1% of site value, after a 10-year transition, and later transactions may be exempt from transfer and landholder duty. For a valuation, these rules affect how a deal is structured and what a buyer will net, not the trading value itself. The duty and tax position is for your lawyer, your accountant or the SRO.
Order book, customers and input costs
Confirmed orders and supply contracts are evidence. A quoted pipeline is not. The valuation weighs them differently and looks at how many of the business's sales go to its largest customers, how long those relationships have run, and when contracts come up for renewal. It also tests margins against the costs that can move fast: imported materials and the exchange rate, and electricity and gas contracts that may reset at renewal.
What the valuer will ask for
- ·Three to five years of financial statements and recent management accounts
- ·Fixed asset register and any recent plant appraisals
- ·Confirmed order book, supply agreements and the quoted pipeline
- ·Aged stock listing showing slow-moving lines
- ·Sales by customer for the top customers over three years
- ·Factory lease, or title details if the business owns the premises
Common questions.
Why use EBIT rather than EBITDA for a manufacturer?+
Because a factory has to keep replacing machines to keep earning. EBITDA leaves that cost out and overstates what an owner can take from the business. Where tax write-offs have distorted depreciation, the valuer uses EBITDA less a normal replacement cost instead.
Does selling shares instead of assets change the value?+
The trading value of the business is the same, but what a buyer nets can differ because of duty, tax and who keeps the liabilities. If the company owns Victorian land, landholder duty may come into it. The valuation states what is being valued; your lawyer and accountant advise on structure.
Will you rely on our own plant appraisals?+
Yes, if they are recent and prepared by a qualified plant valuer, and the report discloses that reliance. Without them, the valuer uses documented estimates or may suggest an appraisal for high-value plant.
What does it cost?+
The fee is fixed before work starts and set by annual turnover: $1,495 + GST under $2 million, $2,495 + GST for $2 million to $3 million, $3,495 + GST for $3 million to $10 million, and a written quote above $10 million. Small reports take 2 business days and medium and large reports 3 business days, counted from when payment and all the information we need are in.
- ·Landholder duty, State Revenue Office Victoria
- ·Understanding commercial and industrial property tax, State Revenue Office Victoria
Talk to a valuer
Tell us what you need valued.
A fifteen-minute call confirms the package, the fixed fee and the delivery date, before you commit to anything.
03 8375 4177Mon to Fri, 9am to 5:30pm Melbourne time
Send the form and we reply within one business day. No documents needed to start.
Small Business Valuation
$1,495 + GST
For a business with annual turnover under $2 million. Signed report in 2 business days. Delivery time starts once payment and all required information have been received. The fee is fixed in writing before we start and never tied to the outcome.
Larger business? Tell us in the form and we recommend the right package. All fees
Last reviewed 10 November 2026 by Business Valuations Melbourne, Level 7, 55 Collins Street, Melbourne.